For decades, Australian business owners operated under a predictable rhythm for superannuation. You ran payroll weekly, fortnightly, or monthly, but your Superannuation Guarantee (SG) contributions were only due at the end of the month following each quarter.
For many small-to-medium enterprises (SMEs), that 28-day quarterly gap served as an informal cash flow buffer. Super liability sat quietly on the balance sheet, allowing businesses to use those funds as working capital to bridge debtor cycles, fund inventory, or manage cash swings.
Under the Australian Taxation Office's (ATO) Payday Super framework—effective from 1 July 2026—that buffer is gone. Employers must now pay employee superannuation at the exact same time as wages, ensuring contributions reach nominated funds within 7 business days of each pay date. While the total dollar amount owed hasn't increased, the rapid acceleration of cash outflows presents a structural shift for SME working capital.
1. The Real Squeeze: Money Out vs. Delayed Money In
The primary challenge of Payday Super isn't the cost of employment—it’s a severe timing mismatch.
Under the old quarterly system, a business could run payroll on week one and retain the superannuation portion in its bank account for up to 90 days before making a bulk settlement to the ATO or super funds. That retained capital provided a vital cushion while waiting for client invoices to clear.
Under the new Payday Super system, that quarterly safety margin disappears. If your business operates on 30-, 60-, or 90-day customer payment terms, your wage and super expenses immediately drain from your bank account every pay period while your cash collections lag behind. When client payments stall, you no longer have the flexibility to hold back superannuation contributions to pay urgent trade suppliers or cover operational overheads.
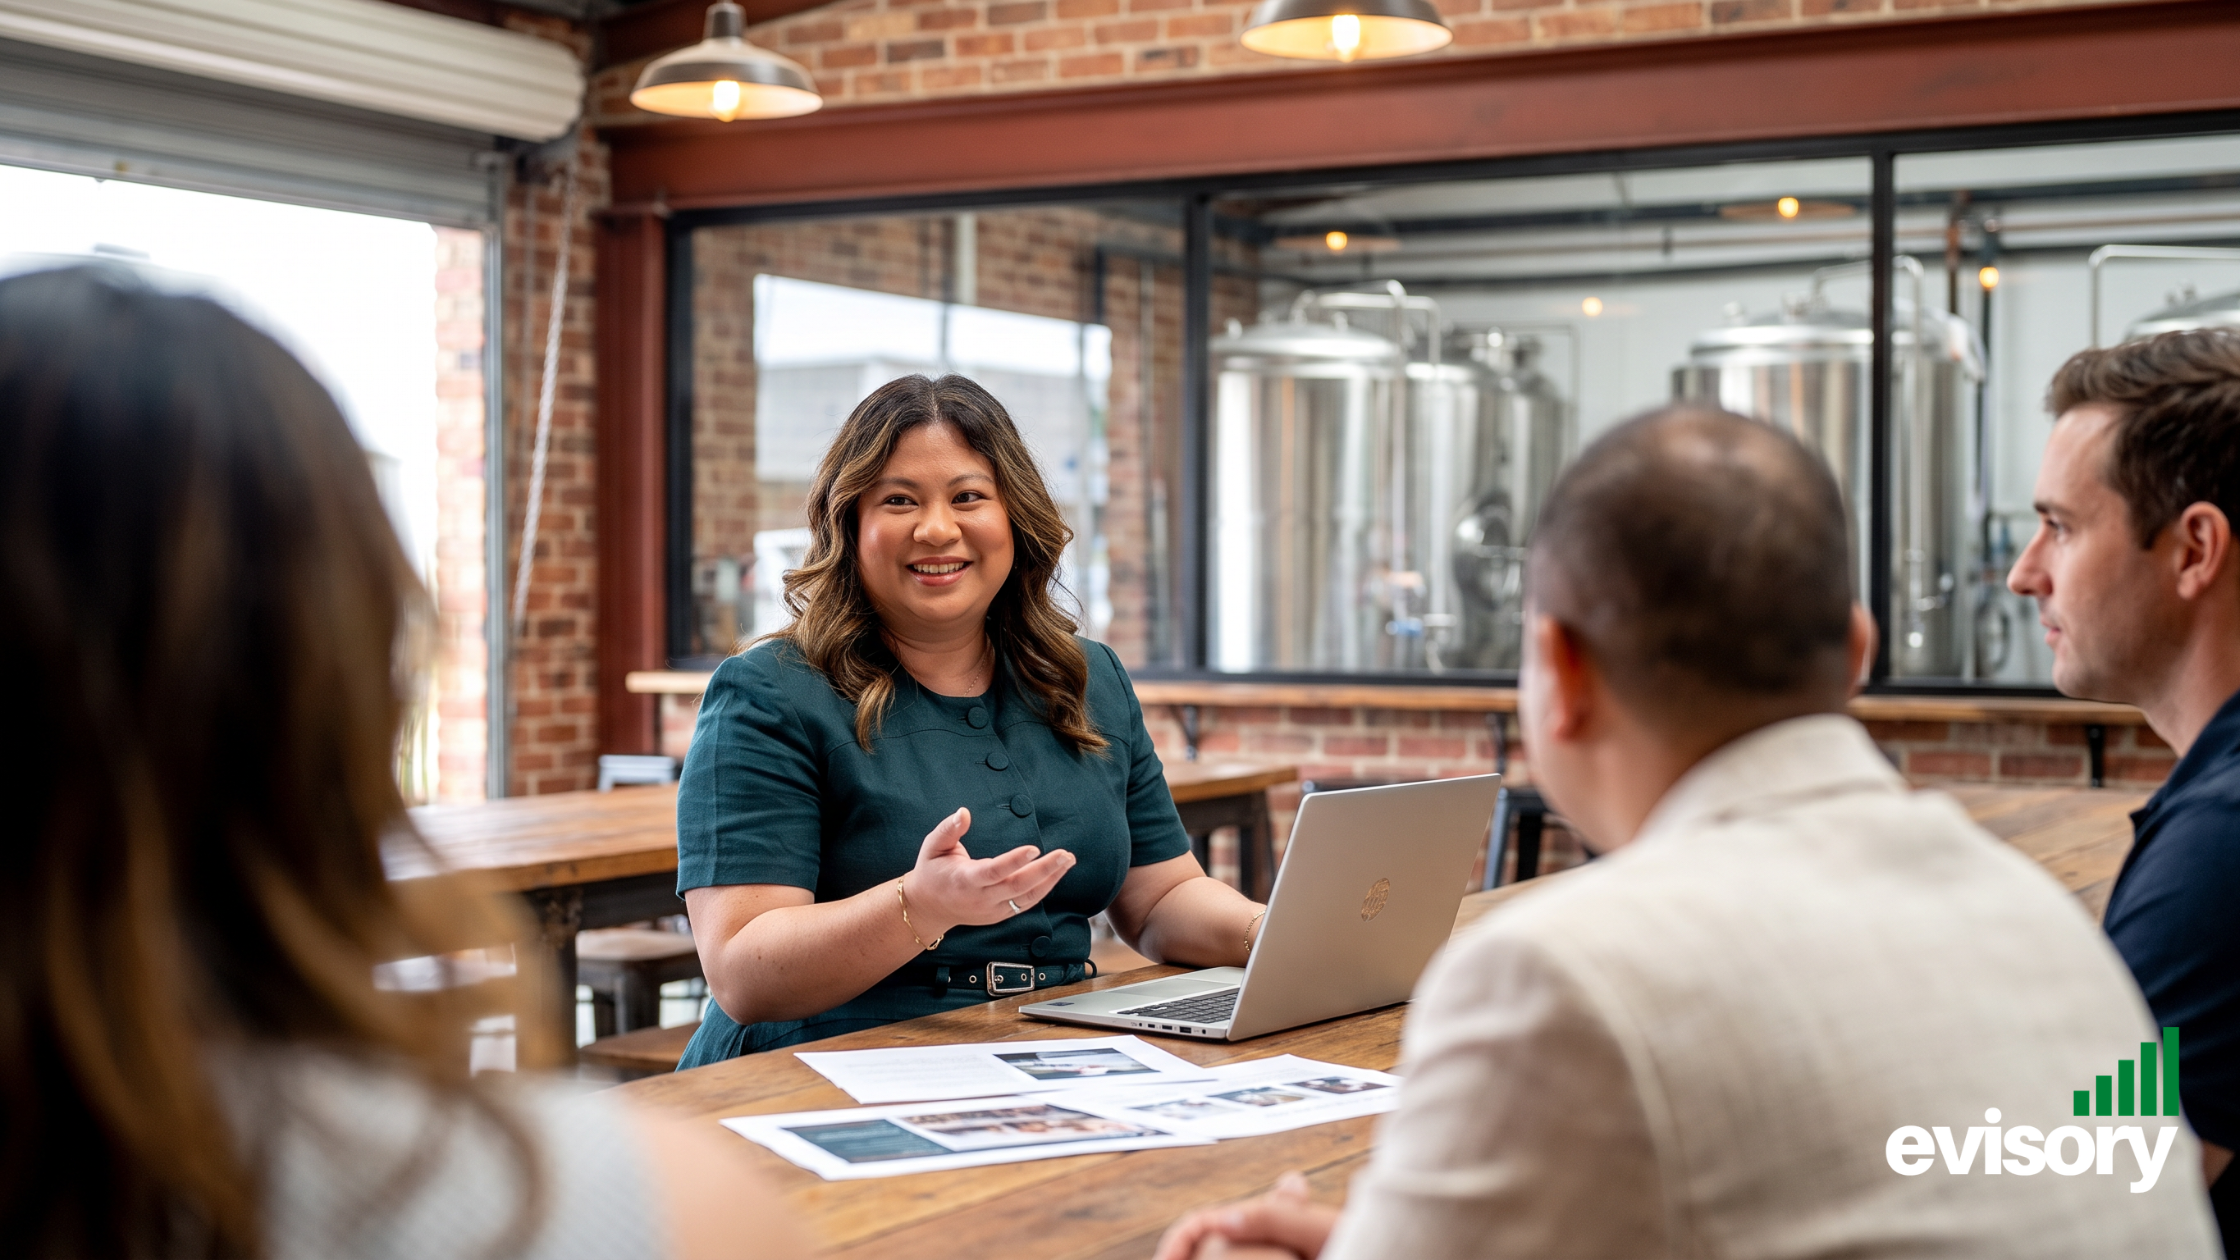
Linda Dang presenting financial strategies and cash flow plans to business clients during a face-to-face consultation meeting.
2. Automated Penalties and ATO Data Matching
Previously, late super payments were often identified during end-of-year reconciliations or manual ATO reviews. Under Single Touch Payroll (STP Phase 2) and real-time super clearing visibility, the ATO now monitors compliance per pay run. Missing a 7-day clearing deadline automatically flags your business, exposing you to severe financial consequences:
Superannuation Guarantee Charge (SGC) Penalties: Non-deductible interest and administrative fees compound automatically for every late pay run.
Director Penalty Notices (DPNs): Company directors face heightened exposure to personal liability for unpaid or delayed superannuation obligations.
Loss of Tax Deductions: Late super contributions immediately forfeit their tax-deductible status, artificially inflating your end-of-year tax bill.
3. How to Prepare Your Business for the Faster Cash Cycle
Adapting to Payday Super requires shifting your focus from retrospective accounting to real-time cash flow management:
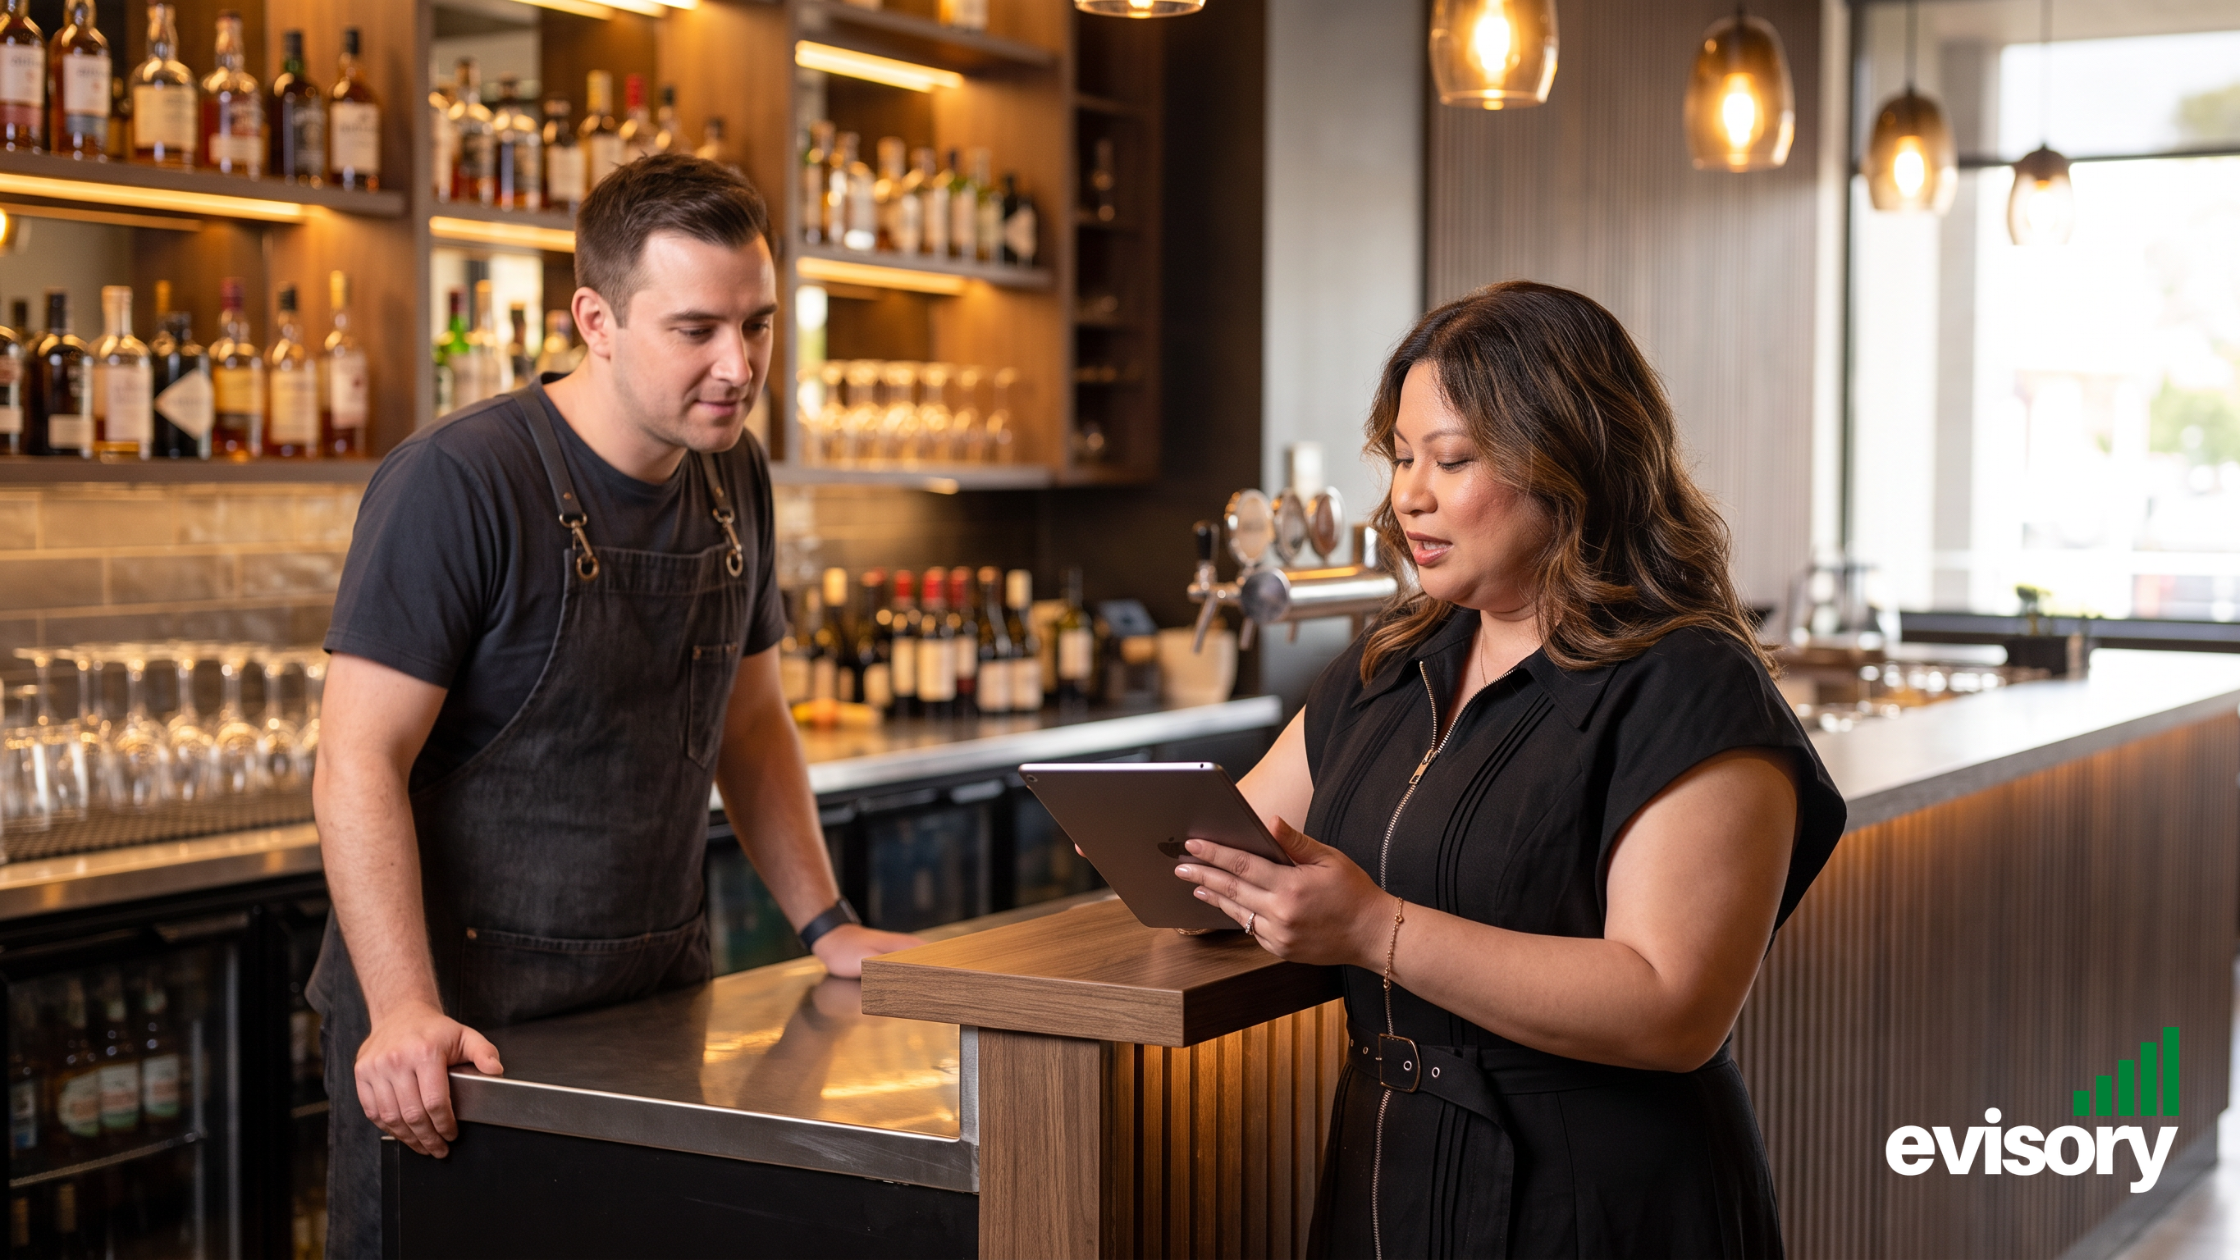
Linda Dang reviewing real-time tablet reports and POS numbers on-site with a venue owner at a bar counter.
Build a 13-Week Cash Flow Forecast: Transition away from static monthly budgets and establish a rolling weekly forecast that incorporates combined wage and superannuation obligations so you can spot cash dips before pay day.
Tighten Your Debtor Collections: Reduce invoice turnaround times by enforcing strict credit terms, setting up automated payment reminders, or offering early-settlement discounts to accelerate cash inflows.
Audit Your Payroll and Clearing House Infrastructure: Review your software setup (such as Xero, MYOB, or Employment Hero) to confirm that processing times comfortably meet the 7-day fund clearing window.
Establish Formal Working Capital Lines: Set up business overdrafts or invoice financing facilities to maintain a legitimate liquidity cushion instead of relying on unpaid tax liabilities.
The Bottom Line
Payday Super has transformed superannuation from a quiet quarterly bill into a weekly operational priority. Business owners who proactively adjust their cash flow models, tighten debtor collections, and upgrade their payroll workflows will navigate this transition smoothly.
Linda Dang working on a laptop with a notebook and coffee at a bright cafe table near a window.
Is your business ready for faster payroll cycles? Contact our advisory team today for a comprehensive cash flow health check and payroll audit before your next pay run.